report
Sri Lanka Insurance Market Audit
Sri Lanka insurance premium growth, claims and financial resilience, with separate regulatory, reporting-period and customer-protection limits.
Record details
- Status
- Updated
- Published
- Updated
- Reviewed
- Publisher
- Research Mind
- Author
- Topics
- Insurance · Financial sector · Sri Lanka
Cite this work
Reference tools
How to cite this work
Choose a referencing style, copy the formatted reference, or download citation data for a reference manager.
Citation target. This reference points to the stable arachchi.ge work record.
Access date. This record may change. Add the date you accessed it if your style requires one.
Selected style APA 7
Arachchige, K. L. (2025). Sri Lanka Insurance Market Audit. Research Mind. https://www.arachchi.ge/works/sri-lanka-insurance-industry/
APA 7 is shown by default. The citation files below remain available when interactive controls are unavailable.
Download citation data
Arachchige, K. L. (2025). Sri Lanka Insurance Market Audit. Research Mind. https://www.arachchi.ge/works/sri-lanka-insurance-industry/
Arachchige, K.L. (2025) Sri Lanka Insurance Market Audit. Research Mind. Available at: https://www.arachchi.ge/works/sri-lanka-insurance-industry/.
Arachchige, Kushan Liyana. 2025. Sri Lanka Insurance Market Audit. Research Mind. https://www.arachchi.ge/works/sri-lanka-insurance-industry/.
Arachchige, Kushan Liyana. Sri Lanka Insurance Market Audit. Research Mind, 23 June 2025, https://www.arachchi.ge/works/sri-lanka-insurance-industry/.
[1] K. L. Arachchige, “Sri Lanka Insurance Market Audit,” Research Mind, Jun. 2025. [Online]. Available: https://www.arachchi.ge/works/sri-lanka-insurance-industry/
1. Arachchige KL. Sri Lanka Insurance Market Audit [Internet]. Research Mind; 2025 Jun. Available from: https://www.arachchi.ge/works/sri-lanka-insurance-industry/
About this audit
Direct long-term and general risk protection
Evidence coverage is limited; the conclusions and excluded uses below show the extent of the findings.
- Evidence checked through
- Edition published
- Methodology
- 1.1.0
- Market definition
- Version 1 · Sri Lanka
Market boundary
Sri Lankan risks and customers
Included activities
- Direct insurance underwriting and servicing
Excluded activities
- Reinsurance as duplicate direct premium
- Standalone broking as underwriting
Changes in this edition
- Bounded financial/resilience panel with reproducible figures and inherited comparability exclusions
- Revised Direction 3 dated 1 October; immutable prior sources and edition retained
- PD-015 public presentation and unchanged canonical/provenance identity
Earlier publication dates and correction notices remain part of this work's history.
Key indicators and their sources
- Long-term insurance assets
- 1,119,957,589,000 LKR 2026-06-30 to 2026-06-30 · observation · not-stated No general measurement-error or causal-effect estimate established. Industry performance — Q2 2026 · Page 1, 2026 total-assets column, Long-term insurance row
- General insurance assets
- 378,950,255,000 LKR 2026-06-30 to 2026-06-30 · observation · not-stated No general measurement-error or causal-effect estimate established. Industry performance — Q2 2026 · Page 1, 2026 total-assets column, General insurance row
Framework coverage
| Module | Coverage | Evidence limitation |
|---|---|---|
| E0 · Identity, decision use and market boundary | complete | See the module analysis. |
| E1 · Market baseline and development | partial | Dependent comparisons, legal effects or quantified customer/digital conclusions remain excluded. |
| E2 · Macroenvironment | partial | Dependent comparisons, legal effects or quantified customer/digital conclusions remain excluded. |
| E3 · Policy, regulation and stakeholders | partial | Dependent comparisons, legal effects or quantified customer/digital conclusions remain excluded. |
| E4 · Industry structure and economics | partial | Dependent comparisons, legal effects or quantified customer/digital conclusions remain excluded. |
| E5 · Customers, segments and demand | partial | Dependent comparisons, legal effects or quantified customer/digital conclusions remain excluded. |
| E6 · Routes to market, suppliers and partners | partial | Dependent comparisons, legal effects or quantified customer/digital conclusions remain excluded. |
| E7 · Competition, alternatives and positioning | partial | Dependent comparisons, legal effects or quantified customer/digital conclusions remain excluded. |
| E8 · Innovation, technology and transition | partial | Dependent comparisons, legal effects or quantified customer/digital conclusions remain excluded. |
| E9 · Outlook, uncertainty and scenarios | partial | Dependent comparisons, legal effects or quantified customer/digital conclusions remain excluded. |
| E10 · Opportunities, threats and critical success factors | partial | Dependent comparisons, legal effects or quantified customer/digital conclusions remain excluded. |
| E11 · Limitations, monitoring and review | complete | See the module analysis. |
Material evidence limitations
- Exclude annualisation, spliced acceleration, forced claims identity, rupee conversion of ambiguous percentages, wrongful denial, insolvency, all-firm rankings and customer-protection inference.
Conclusions this evidence cannot support
- Unique-policyholder or effective-protection estimates from premium/GDP ratios
- Standalone-quarter or annualised premium growth from unresolved Q2 flow metadata
- All-insurer market-share or profitability rankings
- Named-firm solvency inference from an unnamed capital exception
- Measured repository effects or numerical premium forecasts
- Measured CSF weights or certified internal capability
- Paid/outstanding rupee values or rejected-claim residual from ambiguous FSR percentages
- Reinsurance collectability, maturity mismatch or all-firm insolvency from aggregate balance-sheet stocks
- Complete suitability compliance or effect of unresolved August clarification
Sri Lanka’s insurance expansion places greater weight on claims settlement, recoveries from reinsurers and investment liquidity. Premium growth is strong in the regulator’s latest Q2-labelled release, but it does not establish better protection or uniformly stronger earnings. General-insurance pre-tax profit increased while return ratios fell; a named life insurer reported rising premiums and falling profit. The evidence supports a differentiated account of resilience, with capital counterevidence and unresolved claims definitions beside the findings.
E0. Scope and measurement
The market is direct long-term and general insurance written by regulated insurers for Sri Lankan risks. Households and organisations are included. Reinsurance, broking and distribution are relevant inputs or adjacent activities; they are not added again to direct premium. Pension funding and compulsory social security are outside this boundary.
ISIC Rev. 4 6511, life insurance, and 6512, non-life insurance, provide classification anchors. Their international categories do not establish exact equivalence with every Sri Lankan product or regulatory class. The IRCSL insurer register distinguishes permitted classes and entity histories. The audit uses those distinctions rather than treating every listed entity as an identical competitor.
Gross written premium is a flow of insurance business under a stated reporting basis. It is not company valuation, unique policyholders, claims paid or the amount of risk adequately covered. Assets are a stock and require a balance-sheet date. This edition applies methodology 1.1.0, with evidence checked through 20 October 2026. The first assessed edition remains the analytical baseline; this revision updates its financial and regulatory evidence without changing the market boundary.
E1. Financial baseline and the newer Q2 release
IRCSL’s 2025 Annual Report reports approximately LKR 385 billion of direct premium and a premium-to-GDP ratio of 1.18%. Its highlights and narrative contain slightly different premium totals. This audit does not manufacture agreement between them or use their difference as an economic change. The ratio is an aggregate financial measure, not the percentage of people insured.
The quarterly index now lists Q2 2026. The following preserves the reporting labels of that release:
| Measure | Q2 2026 release, LKR billion |
|---|---|
| Direct gross premiums, total | 222.059 |
| Long-term gross premiums | 127.990 |
| General gross premiums | 94.069 |
| Long-term insurance assets | 1,119.958 |
| General insurance assets | 378.950 |
Source: IRCSL Q2 2026, page 1. Original units are LKR thousands; the table rounds to three decimals in billions. Reinsurance is separately reported and is excluded from the direct-premium total. The highlights sheet does not explain whether premium flows are year-to-date or standalone quarter; these premium values retain its Q2 label and are not annualised or joined to a reconstructed quarterly series. Assets use the quarter-end stock basis.
The release also warns that prior-year comparatives were revised and that its broker-asset figure uses 31 March because not all later broker returns were available. Broker assets are therefore excluded from this table. Those qualifications matter when assembling a reusable dataset.
Recalculating the same-release current and comparative values gives direct-premium growth of 20.33%, life 19.30% and general 21.75%. CBSL’s Financial Stability Review 2026 explicitly labels its corresponding rounded rates as H1: 20.3%, 19.3% and 21.8% (printed pages 64–65). This is numerical corroboration, not a reporting-instruction bridge: the underlying IRCSL flow start remains unconfirmed. The FSR’s earlier-period growth rates differ from the current revised table, so no acceleration claim is spliced across vintages. The annual premium-to-GDP ratio above also remains separate from the FSR’s annualised H1 measure; neither measures the proportion of people insured.
E2. Economic mechanisms and inclusion
Premium income can change through new policies, renewal, repricing, insured values and product mix. Asset values can change through accumulated funds, investment returns and valuation effects. This is an analytical decomposition of possible mechanisms; their separate contributions have not been estimated here.
The annual premium-to-GDP ratio can inform a macroeconomic comparison if its numerator, GDP vintage and period are consistent. It cannot determine whether households have enough protection against a particular risk. Income, district, occupation, exposure and policy conditions are needed for that question. Neither a low ratio nor rising premiums guarantees a profitable, accessible new product.
E3. Regulation and consumer information
The official statute register identifies the Regulation of Insurance Industry Act No. 43 of 2000 and subsequent amendments. The directions register now lists Revised Direction 3 of 2026, dated 1 October, concerning the suitability of directors, officers, control-function staff and owners. The inspected instrument takes immediate effect and repeals and replaces the 11 March direction (pages 1 and 9).
The regulator serves this revision at the URL formerly labelled as a postponement notice. It is a new source version, not evidence that the September audit misread the earlier notice. This audit records the instrument’s stated scope and commencement; it does not establish compliance or enforcement. The August clarification to Direction 4 remains a separate unresolved operative-text question, and the suitability annex has not been evaluated as a complete compliance test.
The research implication is to examine the information available to customers at quotation, purchase, renewal and claim. An information requirement is relevant evidence of the regulatory approach; it does not prove comprehension, fair treatment or effective enforcement.
E4. Industry economics
Long-term and general insurance need separate accounts. Their products, liabilities and financial reporting questions differ, and the regulator’s own table separates them. Reinsurance supports risk transfer while introducing a different transaction and counterparty relationship. Adding its premium to direct business would blur the audit boundary.
IRCSL’s Q2 commentary distinguishes compliance with the minimum capital-adequacy ratio from a minimum-total-available-capital exception for one unnamed composite insurer. This cannot support an unqualified claim that every firm is equally sound, or an inference about a named firm’s position. The report does not issue solvency ratings. IRCSL Q2 highlights, page 1
Premiums, profit and financial returns answer different questions
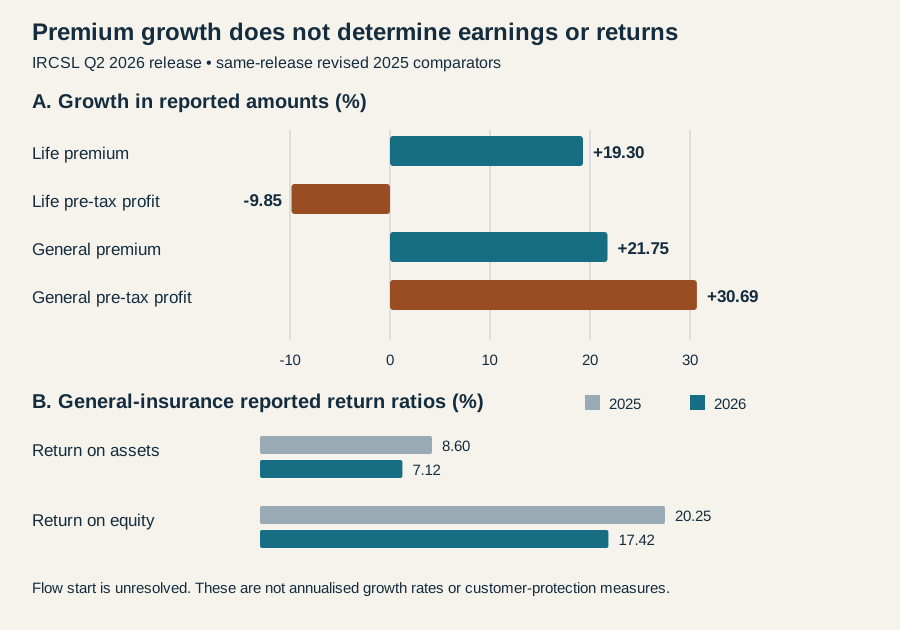
Figure 1. Reproduction from IRCSL’s Q2 2026 highlights, pages 1–3. Growth uses current and revised comparative values from the same release; the source’s unresolved flow start is retained. Return ratios are reported measures, not recalculated with ending assets or equity. Values and formulas are available in the figure data.
General-insurance pre-tax profit rose 30.69%, while reported ROA fell from 8.60% to 7.12% and ROE from 20.25% to 17.42%. Profit in rupees and returns on a capital base can move differently; lower return ratios alone do not establish lower nominal profit. These sector aggregates do not establish every insurer’s experience.
Union Assurance’s six-month accounts provide a different, explicitly dated life-insurer example: gross written premium increased 15.38%, but pre-tax profit fell 32.87% and profit after tax fell 37.21%. Prior pre-tax profit included LKR 170.818 million of associate earnings, absent in the current period. The company continued SLFRS 4 for this interim under the stated temporary treatment; its expected SLFRS 9/17 transition creates a future comparability obligation (pages 2, 12–13). This case is not a general-insurance or national earnings estimate, and no internal-capability rating follows from it.
Catastrophe claims require a development record
| Snapshot | Received claims | Paid or outstanding measure | Interpretation retained |
|---|---|---|---|
| IRCSL, 19 January 2026, released 23 January | 24,549 claims; estimated LKR 58.494 billion | LKR 5.140 billion paid, including advances and ex-gratia | Received estimates and cash payments are different stages; neither is final incurred expense |
| CBSL FSR, end H1 2026 | LKR 57.0 billion received | 44.5% paid; 49.5% outstanding as stated | Count/value basis of these percentages remains unresolved; no rupee conversion or rejected-claims residual |
Sources: IRCSL’s dated release and FSR 2026, printed pages 65–66. The FSR passages were inspected in a retained copy; the current publisher download could not be retrieved, so publisher byte identity and the absence of later corrections are not established. The snapshots are not a consistent development series: scope, estimate revisions and claim development have not been reconciled. Outstanding claims do not establish wrongful denial. Nor can the FSR’s 152.9% comparison be reproduced exactly using its rounded LKR 57.0 billion numerator and the current Q2 claims row: those inputs give 152.22%. The denominator/vintage difference remains unresolved and that ratio is excluded from the argument.
Recoveries and investments connect claims to liquidity
General insurers’ reinsurance receivables reached LKR 69.580 billion, up 161.90% against the revised Q2 comparator, and represented 18.36% of general-insurance assets. A receivable is an asset awaiting collection, not cash available for settlement. Claims payments before recovery can create financing needs; collection timing, reinsurer credit quality and disputes determine the mechanism. The aggregate does not identify overdue, impaired or uncollectable balances.
Life and general insurers together held LKR 171.188 billion in deposits, up 23.39%, corroborating the FSR’s rounded LKR 171.2 billion and 23.4%. Their government-debt holdings were 47.05% of their combined assets. Including the separately reported reinsurer produces 47.26%; the population therefore matters when interpreting the FSR’s rounded 47.0%. These balances link insurers to bank and sovereign exposures but do not measure duration mismatch, immediately withdrawable liquidity or a loss forecast.
Capital provides material counterevidence to a blanket fragility claim: IRCSL reports long-term and general CARs of 313% and 286%, respectively, and says insurers met the minimum CAR requirement, separately identifying an unnamed composite insurer’s minimum-available-capital exception. Aggregate capital headroom does not remove settlement-timing risk or reveal firm-level dispersion. The audit does not infer insolvency or identify that unnamed firm.
A fuller economic comparison still needs aligned insurer accounts, liability and asset definitions, reinsurance arrangements and claims development. The source figures are an exposure and earnings panel, not a profitability ranking or test of internal risk controls.
E5. Customers, segments and demand
The practical demand question is whether a product meets a customer’s risk at an affordable total cost and remains useful when a claim occurs. Premium volume does not establish that relationship. Distinct research populations could include households seeking life protection, users of motor cover and organisations transferring property or liability risks; their needs should not be combined into an undefined average buyer.
A useful inclusion dataset would record unique active customers, relevant sums insured, renewal and lapse rates, claim decisions and turnaround, complaints and geographic/income coverage. These are proposed research measures, not results of a survey performed for this audit. No numerical estimate of uninsured demand or willingness to pay is claimed.
E6. Distribution, partners and data
The insurer register establishes legal entities and permitted business classes. It also records name changes and segregation of former composite businesses. These details matter when matching company accounts across time. A brand or group name is not a stable substitute for the relevant legal entity and insurance class. IRCSL company register
Distribution and servicing involve insurers and intermediaries, while the announced central data repository introduces a shared information dependency. Research should examine who supplies information, how errors are corrected and how a customer reaches support. The present inspection does not establish channel-level acquisition costs, intermediary productivity, data completeness or internal operating performance.
E7. Competition and alternatives
The number of registered entities is not a concentration measure. A defensible comparison requires consistent company-level premium or policy measures, separation of long-term and general business, entity continuity and a stated period. A change of name or a split should not create a fictitious new competitor in a time series.
Price, cover, exclusions, claims service and distribution can all affect a customer’s alternatives. Savings or informal coping arrangements may also be relevant to a particular risk, but their substitution for insurance has not been measured here. The audit therefore does not publish market-share rankings, a top-five concentration figure or a scored five-forces assessment.
E8. Digital infrastructure and innovation
IRCSL’s 20 February 2026 repository announcement describes a platform with CRIB, starting with motor insurance and intending later inclusion of health and life. It presents better risk assessment, fraud detection and customer processing as expected benefits. This establishes the announced programme and intended sequence, not measured nationwide coverage or realised savings.
The useful tests are data completeness, duplicate and erroneous records, correction time, access controls, customer processing time and differential effects across groups. A launch notice cannot establish successful implementation. No measured reduction in fraud, exclusion or claims delay is claimed.
E9. Outlook and scenarios
An effective-protection pathway would combine clearer product information, suitable pricing and dependable claims service with improved evidence about underserved customers. A friction pathway would show nominal premium growth without corresponding improvement in retention, claims experience or access. A digital-error pathway would show benefits constrained by incomplete or inaccurate shared data.
These are conditional analytical scenarios, with no assigned probabilities or premium forecasts. Their signals should be measured with consistent definitions. New quarterly statistics, an operative regulatory change, a material revision or published repository outcome data would trigger reassessment.
E10. Opportunities, threats and critical success factors
The conditional opportunity is to use better information and service to match protection to specific needs. The corresponding threat is to interpret financial expansion or a digital launch as proof that customer outcomes have improved. The evidence supports investigating these mechanisms; it does not establish their economic magnitude.
| Analytical success factor | Evidence to monitor | What would change the assessment |
|---|---|---|
| Understandable, appropriate protection | Product comprehension, relevant cover and exclusions, renewal/lapse | Evidence of different customer needs or persistent mismatch |
| Dependable claims and financial capacity | Claims experience, aligned capital measures and risk-transfer evidence | Material deterioration or a changed liability/regulatory basis |
| Accessible distribution with accountable data | Customer access, correction routes, data quality and processing time | Evidence that channels or shared data exclude users or retain errors |
| Comparable performance measurement | Stable entities, class/period definitions and transparent revisions | New reconciled data that resolves the present comparison gaps |
Each factor spans several modules and has an observable research test. None has a measured causal weight, and no insurer is certified as meeting it.
E11. Limits and monitoring
All E0–E11 modules were examined. Coverage remains limited for current unique policyholders, effective protection, representative customer behaviour, aligned company comparisons, channel economics and measured digital outcomes. The Q2 premium-period ambiguity, claims-development and percentage-basis gaps, reinsurance collectability, revised-comparator differences and unresolved August clarification remain explicit. The revised October suitability direction is treated separately. Missing observations are not zeros, and no financial or legal conclusion is filled in merely to complete a table.
The next cycle should check IRCSL’s quarterly releases, explicit flow definitions, dated catastrophe-claims development, reinsurance recoveries, company-identity changes and original regulatory instruments, including suitability amendments and the August clarification. The issuer accounting transition also requires fresh period and policy comparability checks. A new usable handbook or return format can resolve the period and comparison questions. A full boundary and CSF reassessment is due by 9 September 2027, with earlier review for a material change or correction.
Zero separate company assessments are selected for this external-sector question. Any later company study requires its own purpose, public evidence threshold and exact verified parent; there is no quota. This revision preserves the original route, publication date, source identity, authorship and prior edition. The 9 September full assessment remains the annual-review baseline; the 20 October revision adds the financial panel and the subsequent regulatory development. Prior source versions and calculations are retained in the research record.
Research transparency
Methods, findings and limits
Methodology
Market Audit methodology 1.1.0. Source-specific periods, original units, revised comparatives and reporting populations are retained. Evidence checked through 20 October 2026; limited coverage.
Key findings
- The latest listed Q2 2026 release reports LKR 222.059 billion of direct premium; unresolved flow metadata prevents a standalone-quarter or annualised interpretation.
- Premium-to-GDP ratios and asset stocks do not measure unique customers or effective protection.
- General insurers report higher nominal pre-tax profit alongside lower returns; reinsurance receivables and bank deposits require separate liquidity and counterparty analysis.
- Revised Direction 3 of 2026 took immediate effect on 1 October; its suitability requirements do not establish compliance or customer outcomes.
- Four analytical success factors have research tests; no measured weights, company certification or digital-outcome claim is made.
Limitations
Unique policyholders, protection adequacy, aligned company/channel comparisons and measured digital effects were not established. Q2 premium-flow metadata, annual-total and catastrophe-claims reconciliation, reinsurance collectability and some operative notice texts remain unresolved. Limited coverage; dependent numerical, ranking, legal/financial and capability uses remain excluded.
Evidence
Sources
- ISIC Rev. 4 6511 — Life insurance
- ISIC Rev. 4 6512 — Non-life insurance
- Annual Report 2025
- Current-year insurance industry performance
- Industry performance — Q2 2026
- Insurance Companies register
- Regulation of Insurance Industry — statute register
- Directions register
- Determinations and reporting-format register
- Statistical handbooks index
- IRCSL announces centralized insurance data repository
- Revised Direction 3 of 2026 — suitability of persons, 1 October 2026
- Cyclone Ditwah claims update, 23 January 2026
- Financial Stability Review 2026, insurance and interconnections sections
- Interim financial statements for the six months ended 30 June 2026
Independence
Funding and disclosures
Funding
No external funding was received for this report or its 2026 evidence update.
Disclosures
The author has no disclosed commission, employment or sponsorship from IRCSL, insurers, reinsurers, brokers, agents, technology providers or the publishers cited here.