report
Sri Lanka Supermarket Retail 2026: Sales, Footfall and Recovery
How Cargills and Keells growth shifted between store traffic and basket values, with Sri Lankan household food demand, finances and reusable source data.
Record details
- Status
- Updated
- Published
- Updated
- Reviewed
- Publisher
- Research Mind
- Author
- Topics
- Supermarket retail · Sri Lanka supermarket industry · Cargills · Keells · Modern trade · Food expenditure · Sri Lanka
Cite this work
Reference tools
How to cite this work
Choose a referencing style, copy the formatted reference, or download citation data for a reference manager.
Citation target. This reference points to the stable arachchi.ge work record.
Access date. This record may change. Add the date you accessed it if your style requires one.
Selected style APA 7
Arachchige, K. L. (2025). Sri Lanka Supermarket Retail 2026: Sales, Footfall and Recovery. Research Mind. https://www.arachchi.ge/works/sri-lanka-supermarket-retail/
APA 7 is shown by default. The citation files below remain available when interactive controls are unavailable.
Download citation data
Arachchige, K. L. (2025). Sri Lanka Supermarket Retail 2026: Sales, Footfall and Recovery. Research Mind. https://www.arachchi.ge/works/sri-lanka-supermarket-retail/
Arachchige, K.L. (2025) Sri Lanka Supermarket Retail 2026: Sales, Footfall and Recovery. Research Mind. Available at: https://www.arachchi.ge/works/sri-lanka-supermarket-retail/.
Arachchige, Kushan Liyana. 2025. Sri Lanka Supermarket Retail 2026: Sales, Footfall and Recovery. Research Mind. https://www.arachchi.ge/works/sri-lanka-supermarket-retail/.
Arachchige, Kushan Liyana. Sri Lanka Supermarket Retail 2026: Sales, Footfall and Recovery. Research Mind, 23 June 2025, https://www.arachchi.ge/works/sri-lanka-supermarket-retail/.
[1] K. L. Arachchige, “Sri Lanka Supermarket Retail 2026: Sales, Footfall and Recovery,” Research Mind, Jun. 2025. [Online]. Available: https://www.arachchi.ge/works/sri-lanka-supermarket-retail/
1. Arachchige KL. Sri Lanka Supermarket Retail 2026: Sales, Footfall and Recovery [Internet]. Research Mind; 2025 Jun. Available from: https://www.arachchi.ge/works/sri-lanka-supermarket-retail/
Abstract
Sri Lanka's listed supermarket businesses expanded through the economic crisis and recovery, but sales growth changed composition. This audit examines comparable-store sales, footfall and basket values at Keells alongside Cargills' retail financial disclosures and national household consumption. It combines issuer annual reports and operating releases with official expenditure, price and regulatory evidence inspected through 19 September 2026. Its contribution is a source-linked longitudinal panel that preserves business boundaries, financial periods and reporting vintages. Keells' same-store sales increased 47.6% in FY2022/23, when both traffic and basket values rose sharply. In FY2023/24 and FY2024/25, traffic grew 12.3% and 14.5% while average basket values declined slightly. Cargills' FY2025/26 external retail revenue reached Rs201.372 billion and operating profit Rs8.769 billion, with 8.5% reported same-store sales growth. National real food consumption in 2025 was approximately back to its 2021 level, although nominal expenditure was 85.95% higher. These findings distinguish business expansion from household recovery and show why shopping frequency alone cannot establish improved welfare. The wider analysis connects distribution, fresh-food handling, customer alternatives, operating costs and dated regulatory changes to observable conditions for sustained performance. Missing company observations and conflicting outlet disclosures remain explicit. The evidence supports conditional monitoring of traffic, volumes, margins and household demand; it does not establish national supermarket shares, consumer price rankings or a numerical market forecast.
Scholarly PDF
Download scholarly PDF · v1.1Cite this version when referring to the PDF. Check this article for corrections and later editions.
Archived edition 1.1 · archive revision 1
Report edition released . Archive published on Zenodo .
Exact-edition DOI: 10.5281/zenodo.23308508
The ZIP includes the same PDF, historical source observations, calculations, figures, citation files and reproduction instructions. Evidence edition e01/s00 has a cutoff and uses methodology 1.1.0. Archiving does not refresh that evidence.
Cite this archived edition
Use this citation for report edition 1.1 and archive revision 1. “Cite this work” above refers to the stable work record, originally published 23 June 2025.
APA 7: Arachchige, K. L. (2026). Sri Lanka Supermarket Retail 2026: Sales, Footfall and Recovery (Version 1.1 (archive revision 1), 1.1). Research Mind. https://doi.org/10.5281/zenodo.23308508
All archived versions of this report use the report-family DOI. Use the exact-edition DOI above when citing these files.
Licences apply by component: CC BY 4.0 covers original report prose, figures, documentation and compilation contributions; MIT covers original Python reproduction code. Consult RIGHTS.json and THIRD_PARTY_NOTICES.md in the ZIP for third-party material, facts, fonts, dependencies and other exclusions.
Data and figures
Data edition e01/s00
Source-linked supermarket operating measures and household food-demand observations, with definitions, calculations and source vintages.
About this audit
Centrally managed, self-service, non-specialised food-predominant retail and its own online fulfilment.
Evidence coverage is limited; the conclusions and excluded uses below show the extent of the findings.
- Evidence checked through
- Edition published
- Methodology
- 1.1.0
- Market definition
- Version 1 · Sri Lanka
Market boundary
Sri Lanka; national context and each named operator’s domestic retail scope remain distinct.
Included activities
- Supermarket store operations
- The same operator’s grocery fulfilment
Excluded activities
- Traditional independent grocery as a focal operator
- Specialist retailers
- Pure marketplaces
- Group manufacturing
Changes in this edition
- Adds the within-operator FY2021/22–FY2024/25 comparable-store history and separately dated FY2025/26/Q1FY2026/27 evidence.
- Reconciles company business scopes, nominal/real national food consumption and annual/interim operating-count differences.
- Provides source-linked observations, reproducible arithmetic, figures and first versioned PDF while preserving the canonical route, original date and WordPress source3201.
Earlier publication dates and correction notices remain part of this work's history.
Key indicators and their sources
- Same store sales growth
- 12.9 percent YoY 2021-04-01 to 2022-03-31 · observation · not-stated Company operating KPI. FY2021/22–2022/23 affected by pandemic/inflation/shopping-pattern distortions. ABV is not price inflation. Annual Report 2023/24 · printed p156; caveat p32/p157
- Same store footfall growth
- 4.5 percent YoY 2021-04-01 to 2022-03-31 · observation · not-stated Company operating KPI. FY2021/22–2022/23 affected by pandemic/inflation/shopping-pattern distortions. ABV is not price inflation. Annual Report 2023/24 · printed p156; caveat p32/p157
- Average basket value change
- 8 percent YoY 2021-04-01 to 2022-03-31 · observation · not-stated Company operating KPI. FY2021/22–2022/23 affected by pandemic/inflation/shopping-pattern distortions. ABV is not price inflation. Annual Report 2023/24 · printed p156; caveat p32/p157
- Same store sales growth
- 47.6 percent YoY 2022-04-01 to 2023-03-31 · observation · not-stated Company operating KPI. FY2021/22–2022/23 affected by pandemic/inflation/shopping-pattern distortions. ABV is not price inflation. Annual Report 2024/25 · printed p171; caveat p34
- Same store footfall growth
- 28.3 percent YoY 2022-04-01 to 2023-03-31 · observation · not-stated Company operating KPI. FY2021/22–2022/23 affected by pandemic/inflation/shopping-pattern distortions. ABV is not price inflation. Annual Report 2024/25 · printed p171; caveat p34
- Average basket value change
- 15.1 percent YoY 2022-04-01 to 2023-03-31 · observation · not-stated Company operating KPI. FY2021/22–2022/23 affected by pandemic/inflation/shopping-pattern distortions. ABV is not price inflation. Annual Report 2024/25 · printed p171; caveat p34
- Same store sales growth
- 12.3 percent YoY 2023-04-01 to 2024-03-31 · observation · not-stated Company operating KPI. FY2021/22–2022/23 affected by pandemic/inflation/shopping-pattern distortions. ABV is not price inflation. Annual Report 2024/25 · printed p171; caveat p34
- Same store footfall growth
- 12.3 percent YoY 2023-04-01 to 2024-03-31 · observation · not-stated Company operating KPI. FY2021/22–2022/23 affected by pandemic/inflation/shopping-pattern distortions. ABV is not price inflation. Annual Report 2024/25 · printed p171; caveat p34
- Average basket value change
- -0.1 percent YoY 2023-04-01 to 2024-03-31 · observation · not-stated Company operating KPI. FY2021/22–2022/23 affected by pandemic/inflation/shopping-pattern distortions. ABV is not price inflation. Annual Report 2024/25 · printed p171; caveat p34
- Same store sales growth
- 14.2 percent YoY 2024-04-01 to 2025-03-31 · observation · not-stated Company operating KPI. FY2021/22–2022/23 affected by pandemic/inflation/shopping-pattern distortions. ABV is not price inflation. Annual Report 2024/25 · printed p171; caveat p34
- Same store footfall growth
- 14.5 percent YoY 2024-04-01 to 2025-03-31 · observation · not-stated Company operating KPI. FY2021/22–2022/23 affected by pandemic/inflation/shopping-pattern distortions. ABV is not price inflation. Annual Report 2024/25 · printed p171; caveat p34
- Average basket value change
- -0.3 percent YoY 2024-04-01 to 2025-03-31 · observation · not-stated Company operating KPI. FY2021/22–2022/23 affected by pandemic/inflation/shopping-pattern distortions. ABV is not price inflation. Annual Report 2024/25 · printed p171; caveat p34
- Supermarket revenue
- 99,773,000,000 LKR (nominal) 2022-04-01 to 2023-03-31 · observation · not-stated EBITDA issuer definition includes interest income/share of equity-accounted PAT and excludes specified FX; not comparable to Cargills operating profit. Annual Report 2023/24 · printed p160
- Supermarket revenue
- 110,977,000,000 LKR (nominal) 2023-04-01 to 2024-03-31 · observation · not-stated EBITDA issuer definition includes interest income/share of equity-accounted PAT and excludes specified FX; not comparable to Cargills operating profit. Annual Report 2024/25 · printed p175
- Supermarket revenue
- 124,349,000,000 LKR (nominal) 2024-04-01 to 2025-03-31 · observation · not-stated EBITDA issuer definition includes interest income/share of equity-accounted PAT and excludes specified FX; not comparable to Cargills operating profit. Annual Report 2024/25 · printed p175
- Same store sales growth
- 17.6 percent YoY 2023-04-01 to 2023-06-30 · observation · not-stated Source-native company measure on the stated business and reference period; preserve source rounding and distinct annual/interim vintages. Annual Report 2023/24 · printed pp157/160
- Same store footfall growth
- 8.8 percent YoY 2023-04-01 to 2023-06-30 · observation · not-stated Source-native company measure on the stated business and reference period; preserve source rounding and distinct annual/interim vintages. Annual Report 2023/24 · printed pp157/160
- Average basket value change
- 8.1 percent YoY 2023-04-01 to 2023-06-30 · observation · not-stated Source-native company measure on the stated business and reference period; preserve source rounding and distinct annual/interim vintages. Annual Report 2023/24 · printed pp157/160
- Supermarket revenue
- 27,614,000,000 LKR (nominal) 2023-04-01 to 2023-06-30 · observation · not-stated Source-native company measure on the stated business and reference period; preserve source rounding and distinct annual/interim vintages. Annual Report 2023/24 · printed pp157/160
- Same store sales growth
- 10.4 percent YoY 2023-07-01 to 2023-09-30 · observation · not-stated Source-native company measure on the stated business and reference period; preserve source rounding and distinct annual/interim vintages. Annual Report 2023/24 · printed pp157/160
- Same store footfall growth
- 10.6 percent YoY 2023-07-01 to 2023-09-30 · observation · not-stated Source-native company measure on the stated business and reference period; preserve source rounding and distinct annual/interim vintages. Annual Report 2023/24 · printed pp157/160
- Average basket value change
- -0.2 percent YoY 2023-07-01 to 2023-09-30 · observation · not-stated Source-native company measure on the stated business and reference period; preserve source rounding and distinct annual/interim vintages. Annual Report 2023/24 · printed pp157/160
- Supermarket revenue
- 27,248,000,000 LKR (nominal) 2023-07-01 to 2023-09-30 · observation · not-stated Source-native company measure on the stated business and reference period; preserve source rounding and distinct annual/interim vintages. Annual Report 2023/24 · printed pp157/160
- Same store sales growth
- 10.7 percent YoY 2023-10-01 to 2023-12-31 · observation · not-stated Source-native company measure on the stated business and reference period; preserve source rounding and distinct annual/interim vintages. Annual Report 2023/24 · printed pp157/160
- Same store footfall growth
- 15.7 percent YoY 2023-10-01 to 2023-12-31 · observation · not-stated Source-native company measure on the stated business and reference period; preserve source rounding and distinct annual/interim vintages. Annual Report 2023/24 · printed pp157/160
- Average basket value change
- -4.3 percent YoY 2023-10-01 to 2023-12-31 · observation · not-stated Source-native company measure on the stated business and reference period; preserve source rounding and distinct annual/interim vintages. Annual Report 2023/24 · printed pp157/160
- Supermarket revenue
- 28,756,000,000 LKR (nominal) 2023-10-01 to 2023-12-31 · observation · not-stated Source-native company measure on the stated business and reference period; preserve source rounding and distinct annual/interim vintages. Annual Report 2023/24 · printed pp157/160
- Same store sales growth
- 10.7 percent YoY 2024-01-01 to 2024-03-31 · observation · not-stated Source-native company measure on the stated business and reference period; preserve source rounding and distinct annual/interim vintages. Annual Report 2023/24 · printed pp157/160
- Same store footfall growth
- 14.4 percent YoY 2024-01-01 to 2024-03-31 · observation · not-stated Source-native company measure on the stated business and reference period; preserve source rounding and distinct annual/interim vintages. Annual Report 2023/24 · printed pp157/160
- Average basket value change
- -3.2 percent YoY 2024-01-01 to 2024-03-31 · observation · not-stated Source-native company measure on the stated business and reference period; preserve source rounding and distinct annual/interim vintages. Annual Report 2023/24 · printed pp157/160
- Supermarket revenue
- 27,358,000,000 LKR (nominal) 2024-01-01 to 2024-03-31 · observation · not-stated Source-native company measure on the stated business and reference period; preserve source rounding and distinct annual/interim vintages. Annual Report 2023/24 · printed pp157/160
- Same store sales growth
- 12 percent YoY 2024-04-01 to 2024-06-30 · observation · not-stated Source-native company measure on the stated business and reference period; preserve source rounding and distinct annual/interim vintages. Annual Report 2024/25 · printed pp172/175
- Same store footfall growth
- 11.9 percent YoY 2024-04-01 to 2024-06-30 · observation · not-stated Source-native company measure on the stated business and reference period; preserve source rounding and distinct annual/interim vintages. Annual Report 2024/25 · printed pp172/175
- Average basket value change
- 0.1 percent YoY 2024-04-01 to 2024-06-30 · observation · not-stated Source-native company measure on the stated business and reference period; preserve source rounding and distinct annual/interim vintages. Annual Report 2024/25 · printed pp172/175
- Supermarket revenue
- 30,029,000,000 LKR (nominal) 2024-04-01 to 2024-06-30 · observation · not-stated Source-native company measure on the stated business and reference period; preserve source rounding and distinct annual/interim vintages. Annual Report 2024/25 · printed pp172/175
- Same store sales growth
- 13.8 percent YoY 2024-07-01 to 2024-09-30 · observation · not-stated Source-native company measure on the stated business and reference period; preserve source rounding and distinct annual/interim vintages. Annual Report 2024/25 · printed pp172/175
- Same store footfall growth
- 12.3 percent YoY 2024-07-01 to 2024-09-30 · observation · not-stated Source-native company measure on the stated business and reference period; preserve source rounding and distinct annual/interim vintages. Annual Report 2024/25 · printed pp172/175
- Average basket value change
- 1.4 percent YoY 2024-07-01 to 2024-09-30 · observation · not-stated Source-native company measure on the stated business and reference period; preserve source rounding and distinct annual/interim vintages. Annual Report 2024/25 · printed pp172/175
- Supermarket revenue
- 30,103,000,000 LKR (nominal) 2024-07-01 to 2024-09-30 · observation · not-stated Source-native company measure on the stated business and reference period; preserve source rounding and distinct annual/interim vintages. Annual Report 2024/25 · printed pp172/175
- Same store sales growth
- 14.2 percent YoY 2024-10-01 to 2024-12-31 · observation · not-stated Source-native company measure on the stated business and reference period; preserve source rounding and distinct annual/interim vintages. Annual Report 2024/25 · printed pp172/175
- Same store footfall growth
- 14.2 percent YoY 2024-10-01 to 2024-12-31 · observation · not-stated Source-native company measure on the stated business and reference period; preserve source rounding and distinct annual/interim vintages. Annual Report 2024/25 · printed pp172/175
- Average basket value change
- 0 percent YoY 2024-10-01 to 2024-12-31 · observation · not-stated FY24/25 Q3 ABV p172 rounds0.0; investor highlights p34 gives0.04. Do not silently combine precision. Annual Report 2024/25 · printed pp172/175
- Supermarket revenue
- 32,029,000,000 LKR (nominal) 2024-10-01 to 2024-12-31 · observation · not-stated Source-native company measure on the stated business and reference period; preserve source rounding and distinct annual/interim vintages. Annual Report 2024/25 · printed pp172/175
- Same store sales growth
- 16.2 percent YoY 2025-01-01 to 2025-03-31 · observation · not-stated Source-native company measure on the stated business and reference period; preserve source rounding and distinct annual/interim vintages. Annual Report 2024/25 · printed pp172/175
- Same store footfall growth
- 19.1 percent YoY 2025-01-01 to 2025-03-31 · observation · not-stated Source-native company measure on the stated business and reference period; preserve source rounding and distinct annual/interim vintages. Annual Report 2024/25 · printed pp172/175
- Average basket value change
- -2.4 percent YoY 2025-01-01 to 2025-03-31 · observation · not-stated Source-native company measure on the stated business and reference period; preserve source rounding and distinct annual/interim vintages. Annual Report 2024/25 · printed pp172/175
- Supermarket revenue
- 32,188,000,000 LKR (nominal) 2025-01-01 to 2025-03-31 · observation · not-stated Source-native company measure on the stated business and reference period; preserve source rounding and distinct annual/interim vintages. Annual Report 2024/25 · printed pp172/175
- Outlets
- 134 count 2024-03-31 to 2024-03-31 · observation · not-stated Snapshot not a sales denominator. Gross openings differ from net increase. Annual Report 2023/24 · printed pp156/159
- Opened during year
- 4 count 2023-04-01 to 2024-03-31 · observation · not-stated Snapshot not a sales denominator. Gross openings differ from net increase. Annual Report 2023/24 · printed pp156/159
- Closed during year
- 1 count 2023-04-01 to 2024-03-31 · observation · not-stated Snapshot not a sales denominator. Gross openings differ from net increase. Annual Report 2023/24 · printed pp156/159
- Outlets
- 138 count 2025-03-31 to 2025-03-31 · observation · not-stated Snapshot not a sales denominator. Gross openings differ from net increase. Annual Report 2024/25 · printed pp170/173
- Opened during year
- 6 count 2024-04-01 to 2025-03-31 · observation · not-stated Snapshot not a sales denominator. Gross openings differ from net increase. Annual Report 2024/25 · printed pp170/173
- Closed during year
- 2 count 2024-04-01 to 2025-03-31 · observation · not-stated Snapshot not a sales denominator. Gross openings differ from net increase. Annual Report 2024/25 · printed pp170/173
- Segment revenue before eliminations
- 103,061,948,000 LKR (nominal) 2021-04-01 to 2022-03-31 · observation · not-stated Scope covers Food City/Express/Food Hall/Cargills Online; revenue before eliminations does not mean tax-inclusive till sales. Annual Report 2022/23 · printed p245; PDF page247
- Intersegment revenue eliminated
- 121,473,000 LKR (nominal) 2021-04-01 to 2022-03-31 · observation · not-stated Scope covers Food City/Express/Food Hall/Cargills Online; revenue before eliminations does not mean tax-inclusive till sales. Annual Report 2022/23 · printed p245; PDF page247
- External segment revenue
- 102,940,475,000 LKR (nominal) 2021-04-01 to 2022-03-31 · observation · not-stated Scope covers Food City/Express/Food Hall/Cargills Online; revenue before eliminations does not mean tax-inclusive till sales. Annual Report 2022/23 · printed p245; PDF page247
- Segment revenue before eliminations
- 145,586,716,000 LKR (nominal) 2022-04-01 to 2023-03-31 · observation · not-stated Scope covers Food City/Express/Food Hall/Cargills Online; revenue before eliminations does not mean tax-inclusive till sales. Annual Report 2022/23 · printed p245; PDF page247
- Intersegment revenue eliminated
- 192,891,000 LKR (nominal) 2022-04-01 to 2023-03-31 · observation · not-stated Scope covers Food City/Express/Food Hall/Cargills Online; revenue before eliminations does not mean tax-inclusive till sales. Annual Report 2022/23 · printed p245; PDF page247
- External segment revenue
- 145,393,825,000 LKR (nominal) 2022-04-01 to 2023-03-31 · observation · not-stated Scope covers Food City/Express/Food Hall/Cargills Online; revenue before eliminations does not mean tax-inclusive till sales. Annual Report 2022/23 · printed p245; PDF page247
- Outlets
- 512 count 2023-03-31 to 2023-03-31 · observation · not-stated 512 physical stores exclude2 dark stores; cannot infer2022 count from openings without closure data. Annual Report 2022/23 · printed pp33–34
- Food city outlets
- 290 count 2023-03-31 to 2023-03-31 · observation · not-stated 512 physical stores exclude2 dark stores; cannot infer2022 count from openings without closure data. Annual Report 2022/23 · printed pp33–34
- Express outlets
- 221 count 2023-03-31 to 2023-03-31 · observation · not-stated 512 physical stores exclude2 dark stores; cannot infer2022 count from openings without closure data. Annual Report 2022/23 · printed pp33–34
- Food hall outlets
- 1 count 2023-03-31 to 2023-03-31 · observation · not-stated 512 physical stores exclude2 dark stores; cannot infer2022 count from openings without closure data. Annual Report 2022/23 · printed pp33–34
- Opened during year
- 32 count 2022-04-01 to 2023-03-31 · observation · not-stated 512 physical stores exclude2 dark stores; cannot infer2022 count from openings without closure data. Annual Report 2022/23 · printed pp33–34
- Dark stores
- 2 count 2023-03-31 to 2023-03-31 · observation · not-stated 512 physical stores exclude2 dark stores; cannot infer2022 count from openings without closure data. Annual Report 2022/23 · printed pp33–34
- Segment revenue before eliminations
- 182,461,966,000 LKR (nominal) 2024-04-01 to 2025-03-31 · observation · not-stated Use financial table, not narrative18.3% operating-profit growth; table implies17.59%. Annual Report 2025/26 · Note29 printed p254; PDF page256
- Intersegment revenue eliminated
- 248,780,000 LKR (nominal) 2024-04-01 to 2025-03-31 · observation · not-stated Use financial table, not narrative18.3% operating-profit growth; table implies17.59%. Annual Report 2025/26 · Note29 printed p254; PDF page256
- External segment revenue
- 182,213,186,000 LKR (nominal) 2024-04-01 to 2025-03-31 · observation · not-stated Use financial table, not narrative18.3% operating-profit growth; table implies17.59%. Annual Report 2025/26 · Note29 printed p254; PDF page256
- Segment revenue before eliminations
- 201,653,207,000 LKR (nominal) 2025-04-01 to 2026-03-31 · observation · not-stated Use financial table, not narrative18.3% operating-profit growth; table implies17.59%. Annual Report 2025/26 · Note29 printed p254; PDF page256
- Intersegment revenue eliminated
- 281,283,000 LKR (nominal) 2025-04-01 to 2026-03-31 · observation · not-stated Use financial table, not narrative18.3% operating-profit growth; table implies17.59%. Annual Report 2025/26 · Note29 printed p254; PDF page256
- External segment revenue
- 201,371,924,000 LKR (nominal) 2025-04-01 to 2026-03-31 · observation · not-stated Use financial table, not narrative18.3% operating-profit growth; table implies17.59%. Annual Report 2025/26 · Note29 printed p254; PDF page256
- Outlets
- 556 count 2026-03-31 to 2026-03-31 · observation · not-stated Annual-report observation supersedes interim for chosen annual vintage; unresolved interim reports560 outlets/17 openings. Annual Report 2025/26 · printed pp30/37
- Opened during year
- 15 count 2025-04-01 to 2026-03-31 · observation · not-stated Annual-report observation supersedes interim for chosen annual vintage; unresolved interim reports560 outlets/17 openings. Annual Report 2025/26 · printed pp30/37
- Dark stores
- 3 count 2026-03-31 to 2026-03-31 · observation · not-stated Annual-report observation supersedes interim for chosen annual vintage; unresolved interim reports560 outlets/17 openings. Annual Report 2025/26 · printed pp30/37
- Same store sales growth
- 8.5 percent YoY 2025-04-01 to 2026-03-31 · observation · not-stated No numeric footfall/basket split disclosed; do not impute. Annual Report 2025/26 · printed p29
- Same store sales growth
- 14 percent YoY approximate 2025-04-01 to 2026-03-31 · observation · not-stated Issuer says~14%; not exact14.0; no ABV calculated from rounded measures. JKH EBITDA grows 75% to Rs.80.01 billion in 2025/26 · 26May2026 full-year highlights, supermarket bullet
- Same store footfall growth
- 14.3 percent YoY 2025-04-01 to 2026-03-31 · observation · not-stated Annual PDF inaccessible this session; directly verified issuer release. JKH EBITDA grows 75% to Rs.80.01 billion in 2025/26 · 26May2026 full-year highlights, supermarket bullet
- Same store sales growth
- 13 percent YoY rounded 2026-04-01 to 2026-06-30 · observation · not-stated Quarter distinct from annual; components rounded to whole percentages; do not claim additive decomposition. Q1 FY2026/27 performance update · Q1FY2026/27 performance highlights, supermarket paragraph
- Same store footfall growth
- 6 percent YoY rounded 2026-04-01 to 2026-06-30 · observation · not-stated Quarter distinct from annual; components rounded to whole percentages; do not claim additive decomposition. Q1 FY2026/27 performance update · Q1FY2026/27 performance highlights, supermarket paragraph
- Average basket value change
- 7 percent YoY rounded 2026-04-01 to 2026-06-30 · observation · not-stated Quarter distinct from annual; components rounded to whole percentages; do not claim additive decomposition. Q1 FY2026/27 performance update · Q1FY2026/27 performance highlights, supermarket paragraph
- Outlets
- 560 count 2026-03-31 to 2026-03-31 · observation · not-stated Conflict with annual556/15. Exclude from selected annual series, retain vintage ledger; cause unresolved. Interim financial statements for the twelve months ended 31 March 2026 · management review printed p1; PDF page3
- Opened during year
- 17 count 2025-04-01 to 2026-03-31 · observation · not-stated Conflict with annual556/15. Exclude from selected annual series, retain vintage ledger; cause unresolved. Interim financial statements for the twelve months ended 31 March 2026 · management review printed p1; PDF page3
- Same store sales growth
- 12.3 percent YoY 2026-01-01 to 2026-03-31 · observation · not-stated Quarterly commentary not full-year KPI. Average basket described flat; not a numerical zero. Interim financial statements for the twelve months ended 31 March 2026 · management review printed p1; PDF page3
- Cyclone affected outlets
- 60 count 2025-04-01 to 2026-03-31 · observation · not-stated Company-reported number of Food City outlets affected to varying degrees by Cyclone Ditwah in late November 2025, within FY2025/26. Event count, not total network stock at 31 March 2026, not a permanent closure count, and not all Sri Lankan stores. Exact incident day and reopening duration are not identified by this observation. No loss, probability or comparable national denominator inferred. Annual Report 2025/26 · Chairman’s Message, printed p29 / PDF page31 (affected outlets); printed p54 / PDF page56 (late November 2025 event timing)
- Ncpi fixed basket cost lkr
- 50,729 LKR/month 2021-01-01 to 2021-12-31 · observation · not-stated Not current actual household spending CBSL Annual Economic Review 2025 · printedp10 Figure1.3;footnote6
- Ccpi fixed basket cost lkr
- 91,880 LKR/month 2021-01-01 to 2021-12-31 · observation · not-stated Not current actual household spending CBSL Annual Economic Review 2025 · printedp10 Figure1.3;footnote6
- Ncpi fixed basket cost lkr
- 88,704 LKR/month 2022-01-01 to 2022-12-31 · observation · not-stated Not current actual household spending CBSL Annual Economic Review 2025 · printedp10 Figure1.3;footnote6
- Ccpi fixed basket cost lkr
- 150,184 LKR/month 2022-01-01 to 2022-12-31 · observation · not-stated Not current actual household spending CBSL Annual Economic Review 2025 · printedp10 Figure1.3;footnote6
- Ncpi fixed basket cost lkr
- 103,383 LKR/month 2023-01-01 to 2023-12-31 · observation · not-stated Not current actual household spending CBSL Annual Economic Review 2025 · printedp10 Figure1.3;footnote6
- Ccpi fixed basket cost lkr
- 176,253 LKR/month 2023-01-01 to 2023-12-31 · observation · not-stated Not current actual household spending CBSL Annual Economic Review 2025 · printedp10 Figure1.3;footnote6
- Ncpi fixed basket cost lkr
- 105,063 LKR/month 2024-01-01 to 2024-12-31 · observation · not-stated Not current actual household spending CBSL Annual Economic Review 2025 · printedp10 Figure1.3;footnote6
- Ccpi fixed basket cost lkr
- 178,438 LKR/month 2024-01-01 to 2024-12-31 · observation · not-stated Not current actual household spending CBSL Annual Economic Review 2025 · printedp10 Figure1.3;footnote6
- Ncpi fixed basket cost lkr
- 105,230 LKR/month 2025-01-01 to 2025-12-31 · observation · not-stated Not current actual household spending CBSL Annual Economic Review 2025 · printedp10 Figure1.3;footnote6
- Ccpi fixed basket cost lkr
- 177,545 LKR/month 2025-01-01 to 2025-12-31 · observation · not-stated Not current actual household spending CBSL Annual Economic Review 2025 · printedp10 Figure1.3;footnote6
Framework coverage
| Module | Coverage | Evidence limitation |
|---|---|---|
| E0 · Identity, decision use and market boundary | complete | See the module analysis. |
| E1 · Market baseline and development | partial | Use is limited to the supported dated findings and conditional mechanisms; prohibited wider inferences remain excluded. |
| E2 · Macroenvironment | partial | Use is limited to the supported dated findings and conditional mechanisms; prohibited wider inferences remain excluded. |
| E3 · Policy, regulation and stakeholders | partial | Use is limited to the supported dated findings and conditional mechanisms; prohibited wider inferences remain excluded. |
| E4 · Industry structure and economics | partial | Use is limited to the supported dated findings and conditional mechanisms; prohibited wider inferences remain excluded. |
| E5 · Customers, segments and demand | partial | Use is limited to the supported dated findings and conditional mechanisms; prohibited wider inferences remain excluded. |
| E6 · Routes to market, suppliers and partners | partial | Use is limited to the supported dated findings and conditional mechanisms; prohibited wider inferences remain excluded. |
| E7 · Competition, alternatives and positioning | partial | Use is limited to the supported dated findings and conditional mechanisms; prohibited wider inferences remain excluded. |
| E8 · Innovation, technology and transition | partial | Use is limited to the supported dated findings and conditional mechanisms; prohibited wider inferences remain excluded. |
| E9 · Outlook, uncertainty and scenarios | partial | Use is limited to the supported dated findings and conditional mechanisms; prohibited wider inferences remain excluded. |
| E10 · Opportunities, threats and critical success factors | partial | Use is limited to the supported dated findings and conditional mechanisms; prohibited wider inferences remain excluded. |
| E11 · Limitations, monitoring and review | complete | See the module analysis. |
Material evidence limitations
- National supermarket market size, channel penetration or operator market shares from selected company revenue or outlets
- Household welfare, unique customers, pure price inflation or causal demand effects inferred from footfall and basket value; Fixed-cohort cumulative same-store sales indices or exact additive growth decompositions from changing rounded KPI populations
- Cross-company profitability or efficiency rankings from incompatible business and accounting measures
- Unverified current outlet counts or missing annual observations filled by extrapolation or copied manuscript claims
- A national online-grocery share or measured causal technology effect from one company channel disclosure
- A complete compliance opinion, legal-risk ranking or current commencement claim unsupported by inspected instruments
- Nationally representative delivery quality, household choice or supplier bargaining-power estimates without suitable observations
- Numerical forecasts, measured causal CSF weights or investment recommendations
Conclusions this evidence cannot support
- National supermarket market size, channel penetration or operator market shares from selected company revenue or outlets
- Household welfare, unique customers, pure price inflation or causal demand effects inferred from footfall and basket value
- Fixed-cohort cumulative same-store sales indices or exact additive growth decompositions from changing rounded KPI populations
- Cross-company profitability or efficiency rankings from incompatible business and accounting measures
- Unverified current outlet counts or missing annual observations filled by extrapolation or copied manuscript claims
- A national online-grocery share or measured causal technology effect from one company channel disclosure
- A complete compliance opinion, legal-risk ranking or current commencement claim unsupported by inspected instruments
- Nationally representative delivery quality, household choice or supplier bargaining-power estimates without suitable observations
- Numerical forecasts, measured causal CSF weights or investment recommendations
On this page
Sri Lanka’s listed supermarket businesses increased customer activity during the recovery, but their sales growth changed character. At Keells, comparable-store sales rose 47.6% in FY2022/23, when both traffic and basket values increased sharply. Growth in the next two years came predominantly through more visits: footfall rose 12.3% and 14.5%, while average basket values fell 0.1% and 0.3%. The distinction matters because increasing shopping frequency can support a retailer’s revenue without demonstrating that households can afford substantially more food.
The national consumption evidence reinforces that distinction. By 2025, real household expenditure on food and non-alcoholic beverages was approximately back to its 2021 level, although nominal expenditure was 85.95% higher. The recovery therefore involved rebuilding consumption after the crisis at a much higher price level. Company growth and household recovery describe different populations and should be interpreted together, without treating either as a measure of national supermarket market share.
Evidence cut-off: 19 September 2026. Company financial years run from April to March; national consumption figures refer to calendar years. Latest verified operating updates extend to Keells’ April–June 2026 quarter. Historical observations retain their original dates.
Where the growth came from
The strongest comparable evidence is the four-year sequence of Keells’ reported same-store sales, footfall and average basket values. These measures concern each year’s comparable-store population; they are not a fixed panel of shops followed unchanged throughout the period.
| Financial year | Same-store sales growth | Footfall growth | Average basket-value change |
|---|---|---|---|
| 2021/22 | 12.9% | 4.5% | 8.0% |
| 2022/23 | 47.6% | 28.3% | 15.1% |
| 2023/24 | 12.3% | 12.3% | -0.1% |
| 2024/25 | 14.2% | 14.5% | -0.3% |
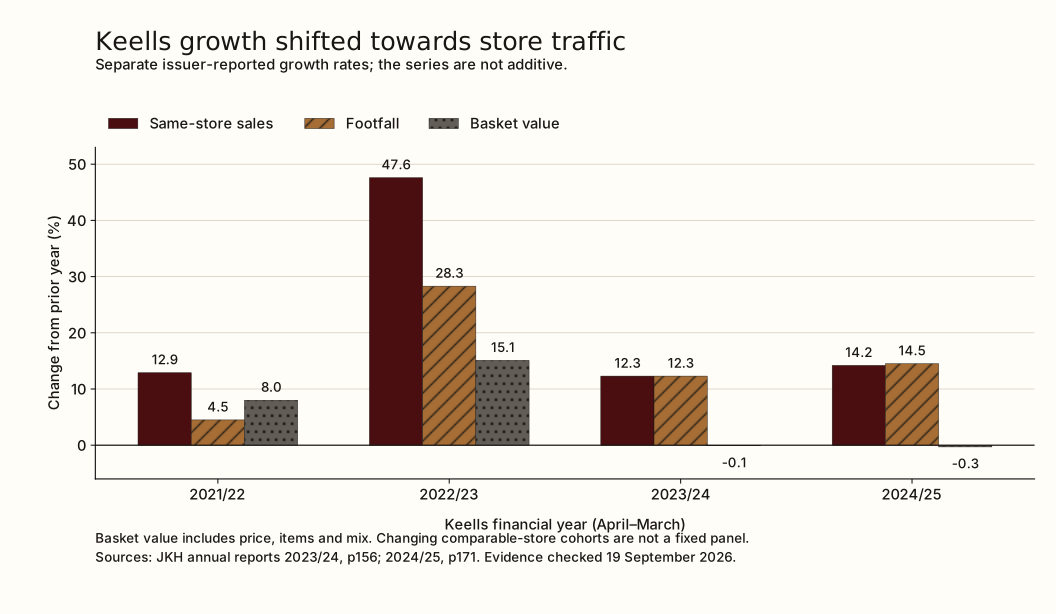
Figure 1. Keells comparable-store growth, FY2021/22–FY2024/25
Company-reported operating measures. Sources: JKH 2023/24 annual report, printed p156, and 2024/25 annual report, printed p171. View Figure 1: Keells’ changing growth composition or download the source-linked observations.
Open full-size figure (SVG) · Download source observations (CSV) · Original edition figure (SVG)
Scroll horizontally when needed, or open the full-size figure. The source observations are available as CSV.
The exceptional FY2022/23 increase needs its crisis context. JKH cautions that pandemic restrictions, inflation and changes in shopping frequency and baskets distorted comparisons involving FY2021/22 and FY2022/23. A 47.6% comparable-store sales increase consequently cannot establish a sustainable growth rate. Traffic and basket measures also combine multiplicatively: 28.3% more visits and a 15.1% higher basket imply approximately 47.67% higher sales, close to the rounded reported figure. Adding the two percentages would omit their interaction.
The subsequent transition appears within the quarterly evidence. In FY2023/24, basket-value growth moved from 8.1% in the first quarter to -3.2% in the fourth, while footfall growth moved from 8.8% to 14.4%. By the fourth quarter of FY2024/25, footfall was 19.1% higher and basket value 2.4% lower, alongside 16.2% same-store sales growth. The annual results therefore conceal a marked change in how sales were generated. These are year-on-year comparisons for each quarter, rather than quarter-on-quarter changes. JKH 2023/24, pp157–160; 2024/25, pp172–175.
A lower average bill does not necessarily mean fewer products purchased. For FY2024/25, JKH attributed the slightly lower basket value to lower selling prices offsetting an increase in items per basket. It also described traffic gains from existing customers visiting more frequently and from new customers. That explanation belongs to the company; the published aggregate measures do not independently identify how much growth each mechanism contributed.
The latest releases suggest another change in composition. Keells reported approximately 14% same-store sales growth and 14.3% footfall growth in FY2025/26. In April–June 2026, it reported 13% sales growth, 6% footfall growth and 7% basket-value growth. Basket value was contributing positively again, while traffic growth had slowed relative to the preceding annual result. Those rounded quarterly percentages do not separate prices, product mix and quantities, and one quarter does not establish a persistent reversal. JKH full-year release, 26 May 2026; Q1 FY2026/27 release.
Business expansion and financial performance
Revenue growth within the named businesses confirms commercial expansion, although reporting boundaries differ. Keells’ supermarket revenue increased from Rs99.773 billion in FY2022/23 to Rs110.977 billion in FY2023/24 and Rs124.349 billion in FY2024/25. The last figure is the supermarket business alone. JKH’s wider Retail segment reported Rs138.337 billion and included other activities; using that total as supermarket revenue would overstate the relevant business. JKH 2023/24, p160; 2024/25, p175.
Keells ended March 2024 with 134 outlets after four openings and one closure. Six openings and two closures brought the network to 138 at March 2025. These dates are deliberate: the more recent company releases used here verify sales and traffic, but do not extend this verified outlet series. Openings, net network additions and comparable-store growth answer different questions. Dividing annual sales by a year-end store count would ignore opening dates, floor areas and format differences.
Cargills’ financial disclosures allow a longer, though incomplete, view of its retail segment. The following observations preserve the missing year rather than interpolate it.
| Financial year | Retail revenue before eliminations, Rs bn | External retail revenue, Rs bn | Retail operating profit, Rs bn |
|---|---|---|---|
| 2021/22 | 103.062 | 102.940 | 3.751 |
| 2022/23 | 145.587 | 145.394 | 6.422 |
| 2023/24 | — | — | — |
| 2024/25 | 182.462 | 182.213 | 7.457 |
| 2025/26 | 201.653 | 201.372 | 8.769 |
Nominal rupees; “—” indicates no observation admitted to this series. Sources: Cargills 2022/23 annual report, printed p245, and 2025/26 annual report, Note 29, printed p254. The earlier segment is named Food Retailing; its stated scope includes Food City, Express, Food Hall and online retail.
Cargills’ revenue before eliminations rose 41.26% in FY2022/23 and 10.52% in FY2025/26, illustrating the difference between crisis-period nominal expansion and the later recovery. Operating profit rose 17.59% in FY2025/26, calculated from the financial table. Approximately Rs281 million of intersegment revenue separates the Rs201.653 billion segment total from Rs201.372 billion of external sales. Revenue before eliminations is an accounting boundary, not a definition of tax-inclusive till receipts. Cargills’ manufacturing activities are separately reported and also sell through other channels, so adding them to retail revenue would further confuse the market boundary.
The latest operating-profit figure equals approximately 4.35% of external retail revenue, compared with 4.09% a year earlier. This improvement supports a finding of stronger reported operating profitability within Cargills’ retail segment. It does not establish the profitability of Sri Lankan grocery retail generally. Keells’ disclosed EBITDA uses a different earnings definition and cannot be placed alongside Cargills’ operating profit as an equivalent margin.
Cargills reported 8.5% full-year same-store sales growth in FY2025/26, attributing growth chiefly to footfall and volume, with only modest basket-value growth. It did not supply the numerical traffic/basket split needed to reproduce Keells’ decomposition. Its historical account provides useful counterevidence: in FY2022/23, management described more frequent shopping alongside fewer items per basket as prices rose. More visits can thus accompany household adjustment to financial pressure. Cargills 2022/23, p26; 2025/26, pp29–30.
Network disclosures also require attention to vintage. Cargills’ 2025/26 annual report records 556 outlets and 15 openings, with three dark stores separately identified. Its earlier twelve-month interim filing reported 560 outlets and 17 openings for the same March 2026 endpoint. This report uses the later annual-report figures; the cause of the discrepancy remains unresolved. They must not be presented as successive expansion observations. The older March 2023 network comprised 290 Food City stores, 221 Express stores and one Food Hall, illustrating why outlet numbers alone cannot measure sales capacity or competitive shares. Annual report, pp30, 37; interim review, printed p1; 2022/23 report, pp33–34.
Household demand recovered at a much higher price level
National food consumption provides a useful counterweight to strong company sales. DCS estimates household expenditure on food and non-alcoholic beverages across all channels, including spending outside supermarkets. Its constant-price series fell in 2022 and again in 2023, then recovered through 2025.
| Calendar year | Current prices, Rs trillion | Constant 2015 prices, Rs trillion |
|---|---|---|
| 2021 | 3.606 | 2.508 |
| 2022 | 5.377 | 2.329 |
| 2023 | 5.895 | 2.308 |
| 2024 | 6.134 | 2.352 |
| 2025 | 6.705 | 2.507 |
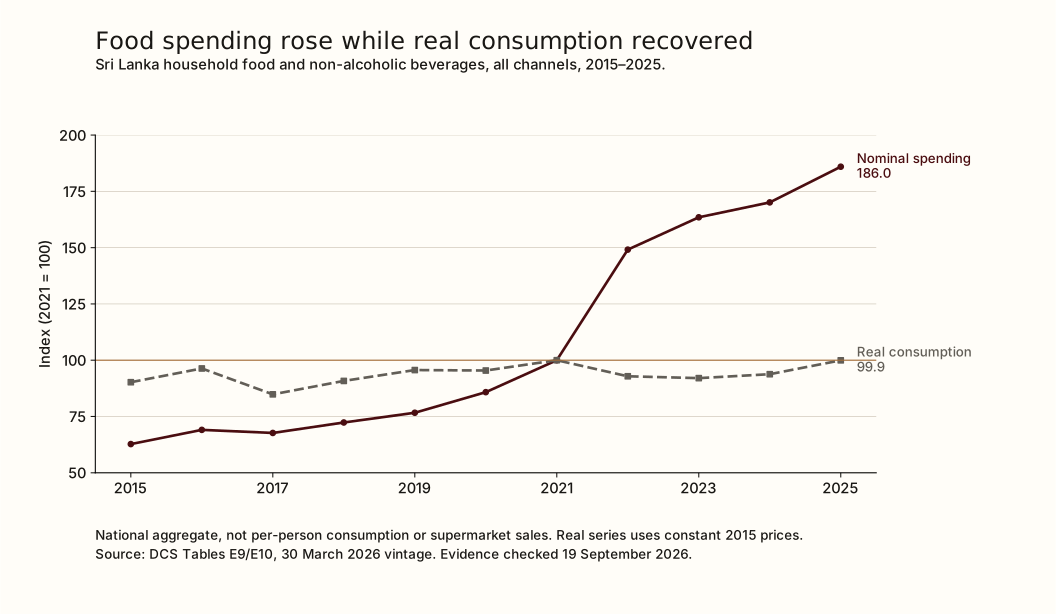
Figure 2. Sri Lanka nominal and real food consumption, 2015–2025
Source: DCS, Household Final Consumption Expenditure 2025, Tables E9 and E10, 30 March 2026 vintage. Values rounded from the published million-rupee observations. Figure 2 compares the nominal and real paths.
Open full-size figure (SVG) · Download source observations (CSV) · Original edition figure (SVG)
Scroll horizontally when needed, or open the full-size figure. The source observations are available as CSV.
By 2025, expenditure measured at 2015 prices was just 0.05% below 2021, while current-price expenditure had increased 85.95%. Much of the apparent expansion in the money spent on food therefore reflected a higher price level over the period. The real recovery is meaningful, but it concerns aggregate consumption: it does not establish that each household regained its earlier consumption, or that per-person quantities were unchanged. The Rs6.705 trillion total is also broader than supermarket turnover and cannot serve as a compatible denominator for a market-share calculation using these company revenues.
Budget exposure differs across households. The pre-crisis 2019 Household Income and Expenditure Survey recorded food at a calculated 28.2% of average urban household expenditure, 36.9% in rural households and 50.9% in estate households. Those are historical shares, not estimates for 2026. They illustrate why a uniform food-price change can impose very different demands on a household budget and why one operator’s average basket cannot describe the whole customer population. DCS HIES 2019 final results, Table 10.
The latest price releases show renewed pressure. Colombo urban food inflation reached 8.5% year on year in August 2026, with headline inflation at 8.0%. The national July release reported 4.9% food inflation and 7.2% headline inflation. These are different geographies and months, not interchangeable estimates of a single supermarket basket. Their immediate commercial implication is that sales-value growth needs to be read alongside traffic and volumes when prices are rising again. DCS August CCPI, p5; July NCPI, Table 3.
Broad wholesale and retail trade grew 1.4% in real value added in Q2 2026, according to the DCS release of 15 September. This supplies economic context but covers a much wider activity boundary and a different accounting measure from supermarket sales. It neither validates nor contradicts double-digit nominal sales growth at an individual chain. DCS Q2 2026 detailed national accounts, p11.
Distribution shapes the economics of fresh food
The supermarket proposition depends on moving products through collection, storage and replenishment quickly enough to maintain availability and quality. Cargills’ FY2025/26 report describes 14 fresh-produce collection centres, five dedicated distribution centres and a central packaged-goods distribution centre. These are different parts of a delivery system: collecting produce near growers, consolidating it for transport, and supplying stores have distinct handling and timing requirements. The counts describe company infrastructure, not its throughput or efficiency. Cargills 2025/26, pp35–37.
For growers and manufacturers, a large network can provide recurring demand and a route into multiple local markets. For the retailer, coordinated purchasing and distribution can improve replenishment and product consistency. The economic benefit depends on stock turning fast enough to cover transport, refrigeration, labour and handling losses. Fresh goods that remain unsold lose value; excessive inventory can therefore weaken returns even while shelves appear well stocked. Published infrastructure counts establish the capacity to coordinate these activities, while actual waste rates, supplier terms and store availability determine the result.
Supplier bargaining power varies across this chain. A widely demanded branded product gives its manufacturer a different negotiating position from a perishable crop with a short selling window. Retail purchasing scale creates negotiating opportunities, but the reports do not establish farmgate margins, payment delays or the distribution of bargaining gains. Vertical integration also changes the relationship: Cargills operates manufacturing businesses separately from retail, while selling manufactured products through traditional distribution as well. Its supermarket footprint is consequently only one part of a broader food system.
Operating costs can offset demand gains. Cargills’ March 2026 interim commentary described pressure from electricity and staff costs despite stronger quarterly sales. Electricity affects refrigeration and storage as well as the shop floor; labour supports checkout, handling and replenishment. This helps explain why higher traffic and a larger network are insufficient tests of commercial success. A retailer must retain a contribution from each additional transaction after serving it. Cargills twelve-month interim report, management review, printed p1.
Cargills also reports that Cyclone Ditwah affected 60 Food City outlets to varying degrees during FY2025/26, while road closures and access problems disrupted logistics. This company account makes the exposure concrete: geographic reach depends on functioning collection and delivery routes during local disruption. Cargills 2025/26, p29.
Expansion also has a local constraint. A new outlet needs a catchment that can sustain its operating costs, suitable premises and reliable delivery. It can attract incremental customers while diverting some visits from nearby branches. Counts of openings reveal investment in presence; comparable-store performance and financial results show whether the established network continues to produce value. These mechanisms make distribution capability, site selection and repeat purchasing more informative than a simple race to add stores.
Competition and customer choice
Competition takes place around shopping needs and local access. The evidence identifies two large listed networks, but neither their combined revenue nor their outlet counts provides a national concentration measure. Other chains, independent grocery shops, specialist traders and markets compete for parts of the same household budget. A household can distribute purchases among several channels, so gaining more visits does not necessarily mean replacing its other shopping relationships.
The table sets out the relevant alternatives by shopping task. It compares service mechanisms, rather than claiming a verified national price ranking.
| Alternative | Customer use | What determines the practical value |
|---|---|---|
| Larger chain supermarket | A combined food, household-goods and fresh-food trip | Travel cost, usable assortment, prices of the actual basket, checkout and stock availability |
| Smaller neighbourhood format | Frequent replenishment near home or work | Proximity, opening hours, pack sizes and whether essential items are available |
| Independent or specialist trader | Targeted purchases and locally convenient shopping | Product suitability, quantity flexibility, freshness and the terms of that transaction |
| Online grocery ordering | An order placed without a physical shopping trip | Delivery area, minimum order, fees, substitution policy, payment and fulfilment reliability |
Cargills’ Food City, Express, Food Hall and online operations demonstrate differentiation within one business rather than four independently controlled competitors. Keells’ FY2024/25 disclosure places online activity at approximately 1% of its revenue and about 8,000 orders a month. That is a useful measure of one operator’s channel at that date. It establishes a functioning online route, but the physical network still dominated that company’s reported sales. Cargills 2022/23, pp33–34; JKH 2024/25, p173.
Price competition must be evaluated through a usable basket. A discount on one branded item can coexist with a higher total bill, unavailable products or a delivery charge. Loyalty offers can change the price a qualifying customer pays, while location and convenience affect the full cost of obtaining groceries. The operator panel does not identify the cheapest channel, and basket-value growth cannot answer that question because the contents of the average basket also change.
For established retailers, the opportunity is to become a reliable choice for repeated shopping missions. For entrants, the challenge is to assemble suppliers, locations, inventory systems and working capital before achieving that repeat demand. Online ordering reduces some physical browsing requirements but retains the need to pick, store and deliver actual goods. These conditions imply meaningful execution requirements; they do not prove that new entry is impossible or that existing firms can set prices without competitive constraint.
Product controls and customer data
Regulatory change affects the way products enter the network and the way retailers use customer information. The Ministry of Health’s Food (Labelling and Advertising) Regulations 2026 took effect on 1 July 2026, with an exclusion for food manufactured before commencement and specified exceptions. Retailers and suppliers need to distinguish the applicable stock and product requirements when accepting goods, checking labels and preparing advertising. Traceability from supplier to shelf connects these rules to the distribution system described above. Gazette 2494/47, regulations 1–3.
The Consumer Affairs Authority’s published price orders operate at product level. Its current register includes orders concerning bottled water, rice and canned fish. Their scope and amendments matter when assessing an individual item; the existence of a controlled price for one product does not imply a general cap on supermarket margins. Commercial analysis should therefore distinguish regulated items from other prices and from promotion-specific transaction values. CAA section 20 orders.
Customer-data systems create a second operating requirement. Loyalty accounts and online fulfilment can connect purchases to identified people, enabling personalised offers and repeat-order services. They also require choices about what information is collected, who receives it and how long it is retained. The July 2026 commencement order appoints 1 January 2027 for sections 2 and 3, Part I and Part III of the Personal Data Protection Act; this is not a single commencement date for every provision. Gazette 2498/16.
The strategic question is whether these systems improve a useful service: accurate fulfilment, relevant offers or reliable stock planning. A loyalty registration or an app installation cannot by itself establish additional purchasing, better customer retention or higher profitability. Linking operational improvements to repeat orders and contribution would provide stronger evidence of the return from digital investment.
What would sustain the recovery?
The assessment at 19 September 2026, looking through March 2027, is that repeat traffic remains a demonstrated source of listed-operator growth, while renewed basket-value increases require closer interpretation. Three developments would distinguish a broader recovery from nominal expansion under pressure.
Demand broadens if greater purchasing survives the higher price level. Further growth in real national food expenditure, combined with continued comparable-store traffic and favourable item-volume disclosures, would support this interpretation. Strong company sales accompanied by weak real food consumption would instead suggest a narrower result involving operator performance, channel shifts or prices. The two can coexist: one chain can gain business while some households remain constrained.
Pressure intensifies if higher bills replace volume growth. Rising food inflation, slower traffic growth and renewed reports of fewer items per basket would strengthen that reading. April–June 2026 already brought a larger basket-value contribution at Keells, but its disclosure does not isolate the component caused by prices. The next observations should test that distinction, rather than assume that a larger average bill demonstrates improved purchasing power.
Distribution improvements matter when they protect contribution and availability. Better replenishment, fewer losses and efficient fulfilment can support performance even when household spending remains disciplined. Evidence would come from comparable financial margins, stock or waste measures where published, and service indicators. Store openings or infrastructure announcements alone would provide weaker support. Cargills’ latest margin improvement is encouraging for that segment, while its interim cost-pressure commentary shows why the result requires continued observation.
Taken together, these pathways suggest three capabilities to test: offering a useful basket at an acceptable total cost; replenishing fresh and essential goods consistently; and converting repeat demand into earnings after distribution, labour, energy and fulfilment costs. Digital services become commercially valuable when they improve those outcomes for a defined customer group. Their existence is a starting condition, not an achieved return.
The next dated company checkpoint is JKH’s scheduled Q2 FY2026/27 results on 3 November 2026, followed by its investor webinar on 4 November. Cargills’ next available interim filing should be checked for comparable sales measures, operating costs and reconciliation of network counts. The DCS calendar schedules the next national inflation release for 21 September, Q2 expenditure estimates for 23 September, and the revised 2025 household-survey final bulletin for 20 November 2026. These are scheduled source checkpoints, not guaranteed release dates. The household survey should be particularly useful for revisiting the pre-crisis budget profile. Monitoring should preserve the last verified observation when a comparable replacement is unavailable, rather than advance a statistical date merely because the page was revisited. JKH financial calendar.
Methods and reusable evidence
This is an external market audit under Market Audit methodology 1.1. The focal market is supermarket grocery retail in Sri Lanka; neighbourhood, specialist and online alternatives are included where they compete for the same shopping needs. Cargills’ retail segment and JKH’s supermarket business supply the longitudinal company evidence. Household consumption and broad trade statistics describe their surrounding economy, with their original populations and units retained.
The evidence set combines issuer annual reports and operating releases with DCS national accounts and price statistics, and official legal instruments. Financial-table figures, management operating indicators and this report’s calculations are distinguished. Monetary company comparisons use nominal rupees and April–March financial years; the household comparison uses calendar years and DCS current- and constant-price series. Reported figures are rounded for reading; the underlying observations preserve source precision, titles, URLs, locators and scope.
Comparable-store growth is checked using (1 + footfall growth) × (1 + basket-value growth) - 1, with growth expressed as decimals. The four annual Keells observations differ from that product by at most 0.12 percentage points, consistent with rounded and aggregated disclosures. This is a reconciliation check, not a causal allocation of sales or a fixed-store index. The quarterly whole-percent disclosure is retained at its published precision. Revenue growth and profit ratios use the stated financial-table denominators, and intersegment revenue is excluded when reporting external sales.
Source vintages are retained where they change interpretation. The Cargills annual report supplies the selected March 2026 network count and financials; the earlier interim count remains recorded as a conflicting observation. The financial table implies 17.59% operating-profit growth, rather than the 18.3% stated in the annual narrative, so the table governs the calculation. Historical Keells quarter revenues reconcile to within Rs1 million in FY2023/24 and exactly in FY2024/25, at the reports’ stated million-rupee precision.
The principal limits are substantive. Two listed businesses cannot represent every retailer; comparable-store populations can change; visits are not unique customers; basket values combine prices, quantities and mix; and accounting revenue is not a uniform measure of consumer expenditure. There is no defensible national supermarket market-share estimate in this evidence set. No consumer survey, matched shopping-basket audit or supplier-contract study was conducted. Accordingly, the report explains observed business growth and market mechanisms without estimating household welfare effects, supplier bargaining outcomes or a national market forecast.
Download the observation CSV, calculation record, source and definition dictionary and source-vintage ledger. The two figures provide separate views of Keells’ operating measures and national nominal and real food demand. Source links and locators allow each measure to be traced back to its reporting boundary and date.
Funding and conflicts of interest
Funding: No external funding was received for this report or its 2026 evidence update.
Competing interests: This is independent market analysis. The author has no disclosed commission, employment or sponsorship from Cargills, John Keells, other retailers, suppliers or the publishers cited here. This report is not investment advice or a recommendation concerning any retailer.
Publication history and corrections
Originally published on 23 June 2025 and revised on 13 August 2026. This full audit, prepared on 19 September 2026 and released on 21 September 2026, adds the longitudinal operator panel, reporting-scope reconciliation, national consumption path and reusable evidence files. The original publication identity and canonical article address are retained; the accompanying PDF is edition 1.1, with evidence checked through 19 September. The earlier sealed preparation file is retained; edition 1.1 corrects the release date after publication was postponed.
Corrections can be submitted through the correction form. Please identify the affected statement or observation, its source and reporting period so that the article, figures and data can be corrected consistently.
Further research
A matched basket across local shopping alternatives would test practical affordability, including travel and delivery costs. Household purchasing records could distinguish new customers from more frequent visits and show how purchases move between channels. Supplier payment, rejection and waste measures would clarify how the gains and costs of organised distribution are shared.
References
Numbered references correspond to the PDF edition. Descriptive links in the article identify the sources used for individual claims.
- John Keells Holdings PLC. Annual Report 2023/24. Printed pp. 32, 156–160: comparative-store measures, network movement and supermarket financials. Source JKH24. Accessed 2026-09-19. Publication date not established.
- John Keells Holdings PLC. Annual Report 2024/25. Printed pp. 34, 170–175: comparable-store measures, outlet movement, online channel and supermarket-only financials. Source JKH25. Accessed 2026-09-19. Publication date not established.
- John Keells Holdings PLC. 2026-05-26. JKH EBITDA grows 75% to Rs. 80.01 billion in 2025/26. 26 May 2026 full-year highlights, supermarket bullet. Source JKH26_RELEASE. Accessed 2026-09-19.
- John Keells Holdings PLC. JKH records EBITDA growth of 26% to Rs. 16.35 billion in Q1. Q1 FY2026/27 performance highlights, supermarket paragraph. Source JKH27Q1_RELEASE. Accessed 2026-09-19. Publication date not established.
- Cargills (Ceylon) PLC. Annual Report 2022/23. Printed pp. 26, 33–34, 244–245: shopping behaviour, store formats, segment scope and financial table. Source CARG23. Accessed 2026-09-19. Publication date not established.
- Cargills (Ceylon) PLC. Integrated Annual Report 2025/26. Printed pp. 29–30, 35–37, 253–254: operating narrative, cyclone effects, distribution, network and Note 29 segment table. Source CARG26. Accessed 2026-09-19. Publication date not established.
- Cargills (Ceylon) PLC. Interim Financial Statements: twelve months ended 31 March 2026. Management review, printed p. 1 / PDF p. 3: Q4 commentary, annual outlet count and openings. Source CARG26_INTERIM. Accessed 2026-09-19. Publication date not established.
- Department of Census and Statistics, Sri Lanka. 2026-03-30. DCS household final consumption expenditure, 2015–2025. PDF p1, Tables E9/E10; PDF p2, Tables E9.1/E10.1. Source RC01. Accessed 2026-09-19.
- Department of Census and Statistics, Sri Lanka. DCS Household Income and Expenditure Survey 2019 Final Results. PDF p8, Table 10; PDF p2 sample description. Source RC06. Accessed 2026-09-19. Publication date not established.
- Department of Census and Statistics, Sri Lanka. 2026-08-31. DCS CCPI August 2026. PDF p1 and p5, section 2.1. Source RC03. Accessed 2026-09-19.
- Department of Census and Statistics, Sri Lanka. 2026-08-21. DCS NCPI July 2026. PDF p1 and p5 (printed p4), Table 3. Source RC04. Accessed 2026-09-19.
- Department of Census and Statistics, Sri Lanka. 2026-09-15. DCS national accounts Q2 2026 detailed note. PDF p11 wholesale and retail trade; PDF p3 agriculture. Source RC05. Accessed 2026-09-19.
- Ministry of Health, Sri Lanka. 2026-06-26. Food (Labelling and Advertising) Regulations 2026, Gazette 2494/47. PDF p1 regulations1–3; PDF p2 exceptions; PDF p4 regulation5. Source RC08. Accessed 2026-09-19.
- Consumer Affairs Authority, Sri Lanka. CAA Orders under section20. Orders list, most recent Order96 dated2026-06-10. Source RC10. Accessed 2026-09-19. Publication date not established.
- Government of Sri Lanka / Data Protection Authority. 2026-07-22. PDPA commencement order, Gazette 2498/16. One-page Gazette, appointment paragraph. Source RC09. Accessed 2026-09-19.
- Department of Census and Statistics, Sri Lanka. DCS Advance Data Release Calendar 2026. Rows1.8/1.11;2.1/2.2;5.1/5.3. Source RC11. Accessed 2026-09-19. Publication date not established.
- John Keells Holdings PLC. Investor relations: financial calendar. Financial calendar: Q2 FY2026/27 results, 3 November 2026; investor webinar, 4 November 2026. Source JKH_CALENDAR. Accessed 2026-09-19. Publication date not established.